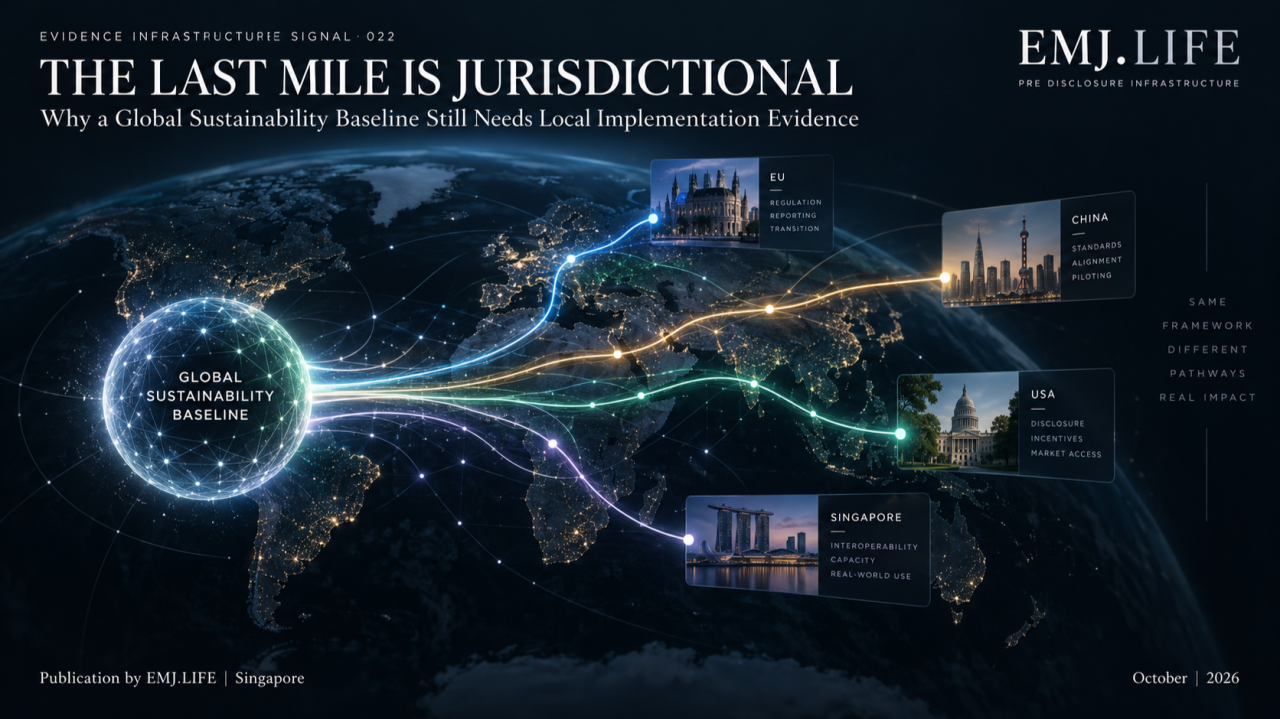
The Last Mile Is Jurisdictional
Why a Global Sustainability Baseline Still Needs Local Implementation Evidence
Signals8SOURCES
Why a Global Sustainability Baseline Still Needs Local Implementation Evidence
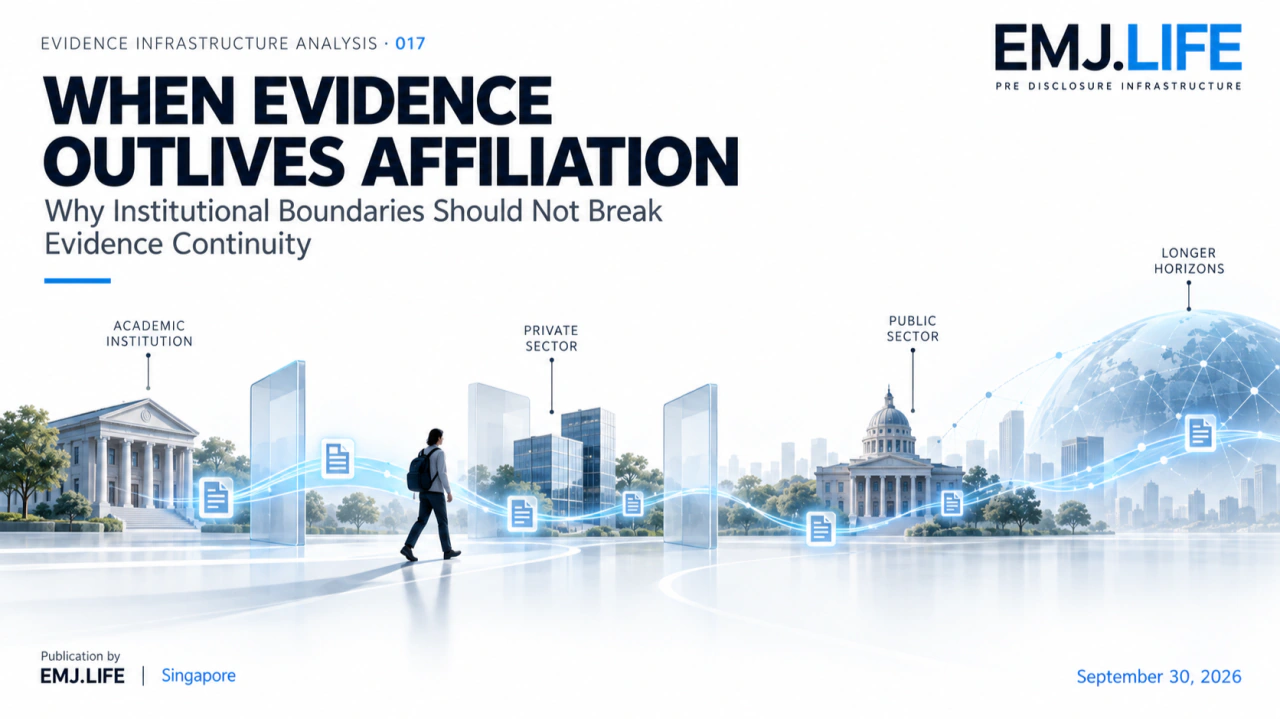
Why Institutional Boundaries Should Not Break Evidence Continuity
What ISSB, GRI and TNFD Reveal About Where Sustainability Complexity Is Moving
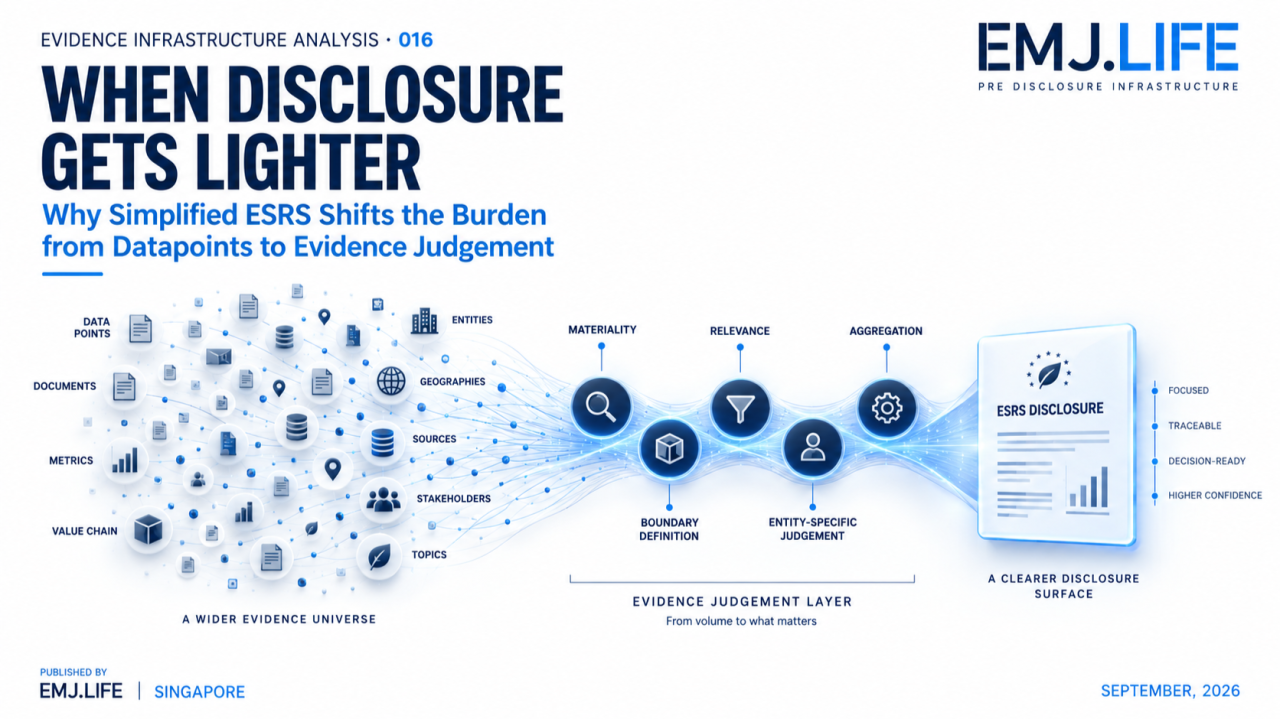
Why Simplified ESRS Shifts the Burden from Datapoints to Evidence Judgement
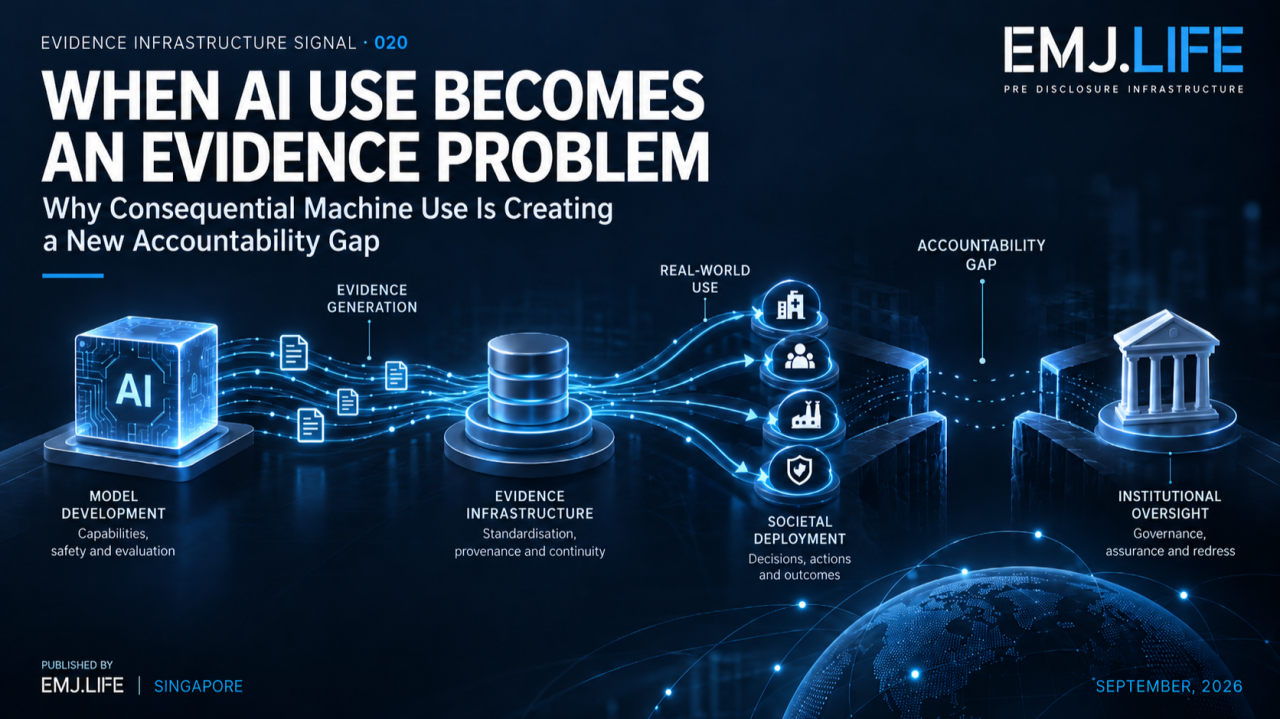
Why Consequential Machine Use Is Creating a New Accountability Gap
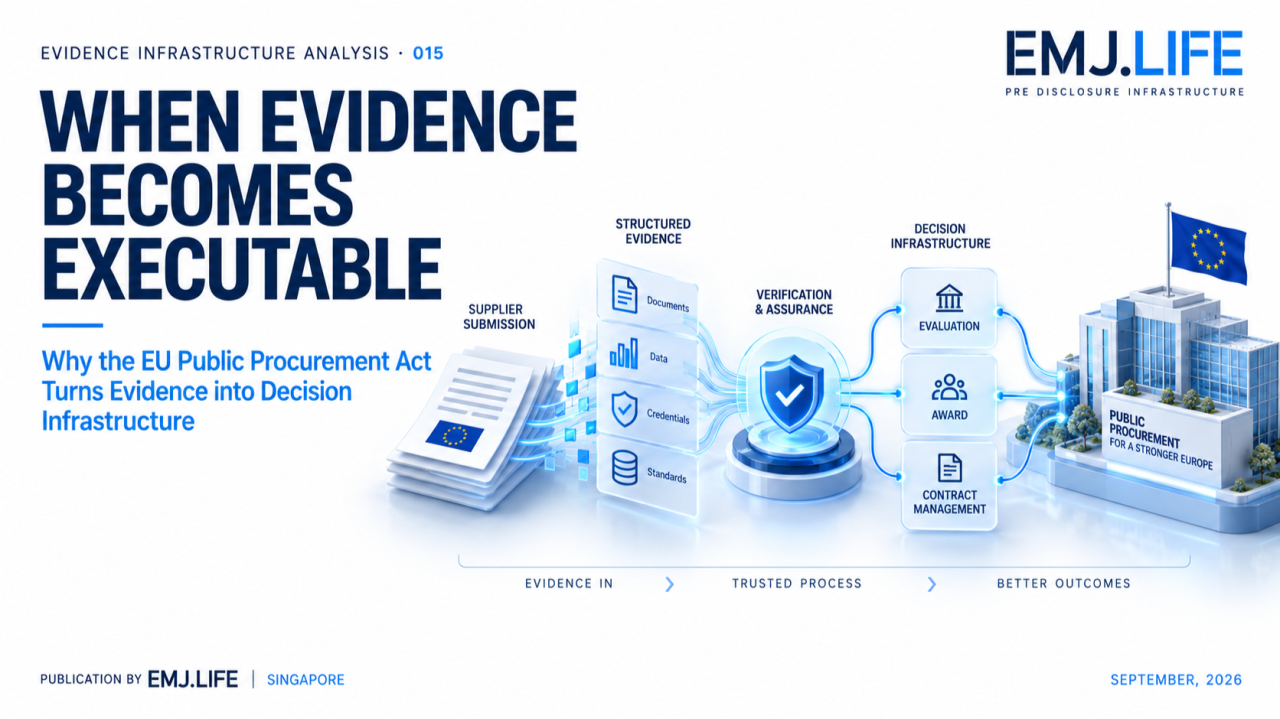
Why the EU Public Procurement Act Turns Evidence into Decision Infrastructure
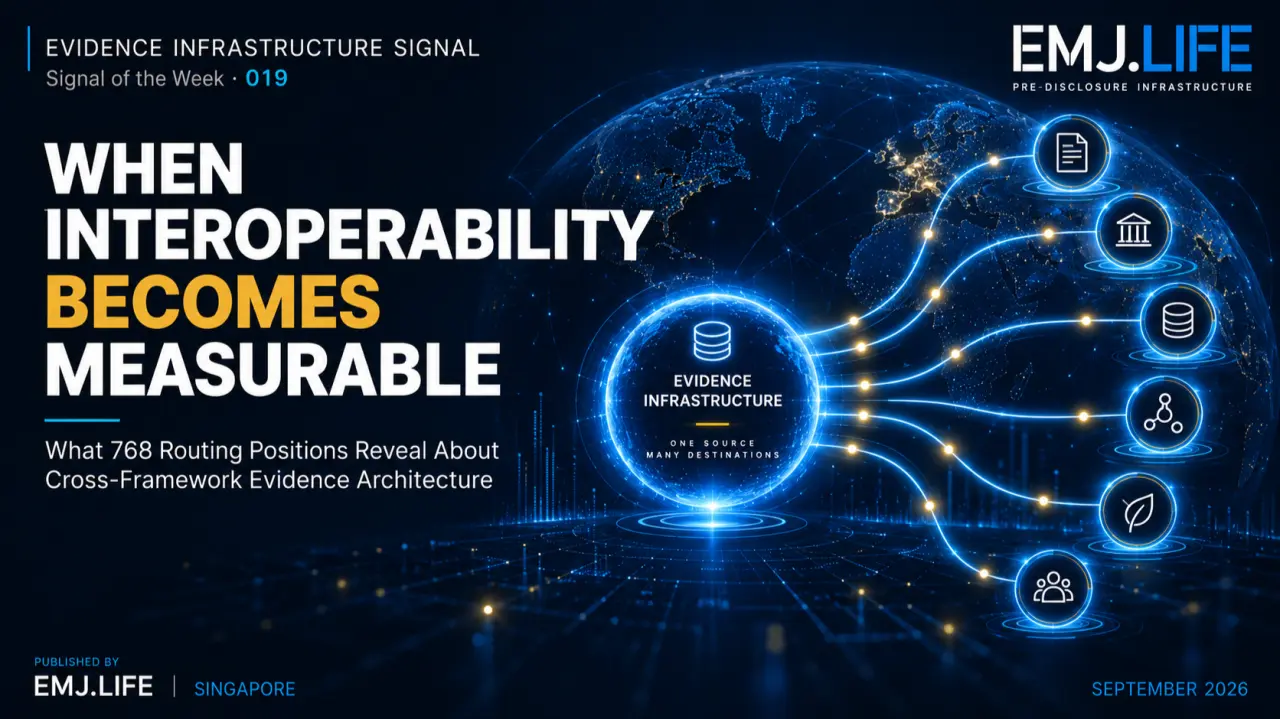
What 768 Routing Positions Reveal About Cross-Framework Evidence Architecture
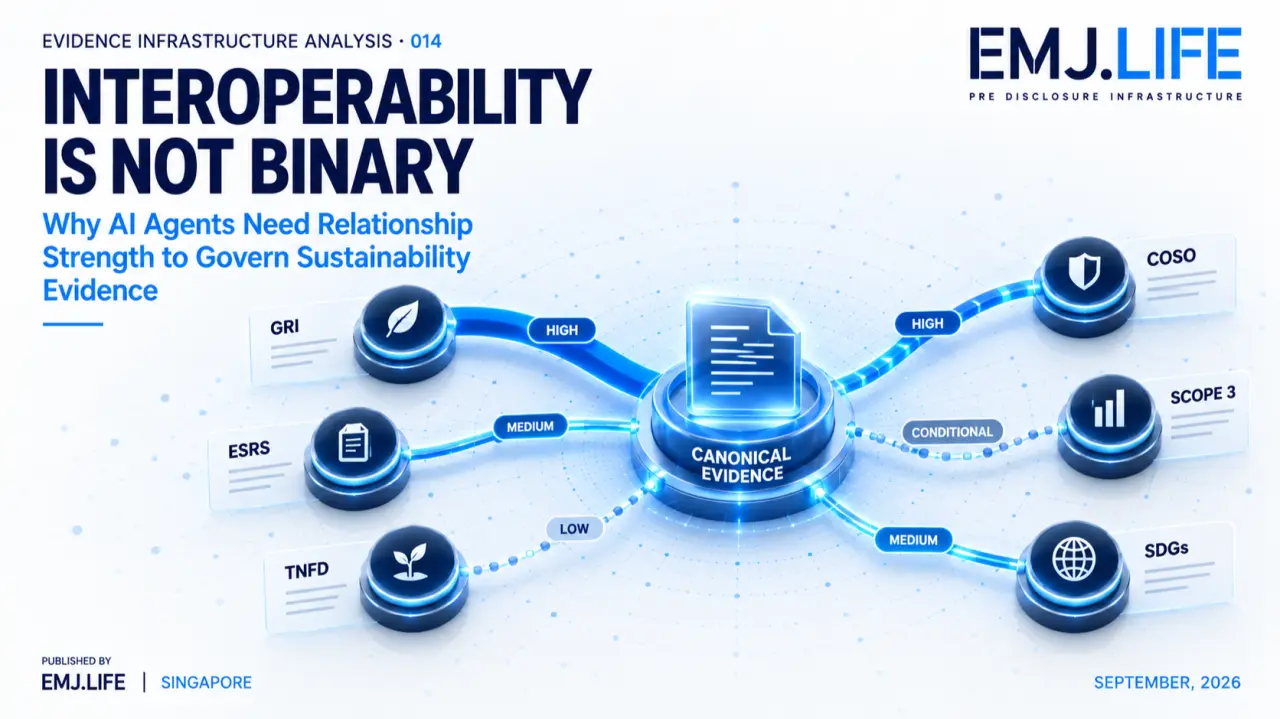
Why AI Agents Need Relationship Strength to Govern Sustainability Evidence
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and candidate GRI topic and disclosure routes. The mappings preserve the distinction between financial materiality and GRI impact materiality.
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and materiality-governed ESRS topic routes, with provenance separated between authentic EU legal texts and EFRAG support materials.
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and candidate TNFD nature-related routes, including LEAP-related evidence relationships.
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and candidate COSO control-support relationships across internal control, enterprise risk and sustainability-reporting contexts.
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and candidate GHG Protocol Scope 3 category and accounting-process routes.
An independent EMJ.LIFE methodology publication mapping 128 MME task positions to licensed IFRS ISSB and SASB source relationships and candidate United Nations Sustainable Development Goal and Target routes.
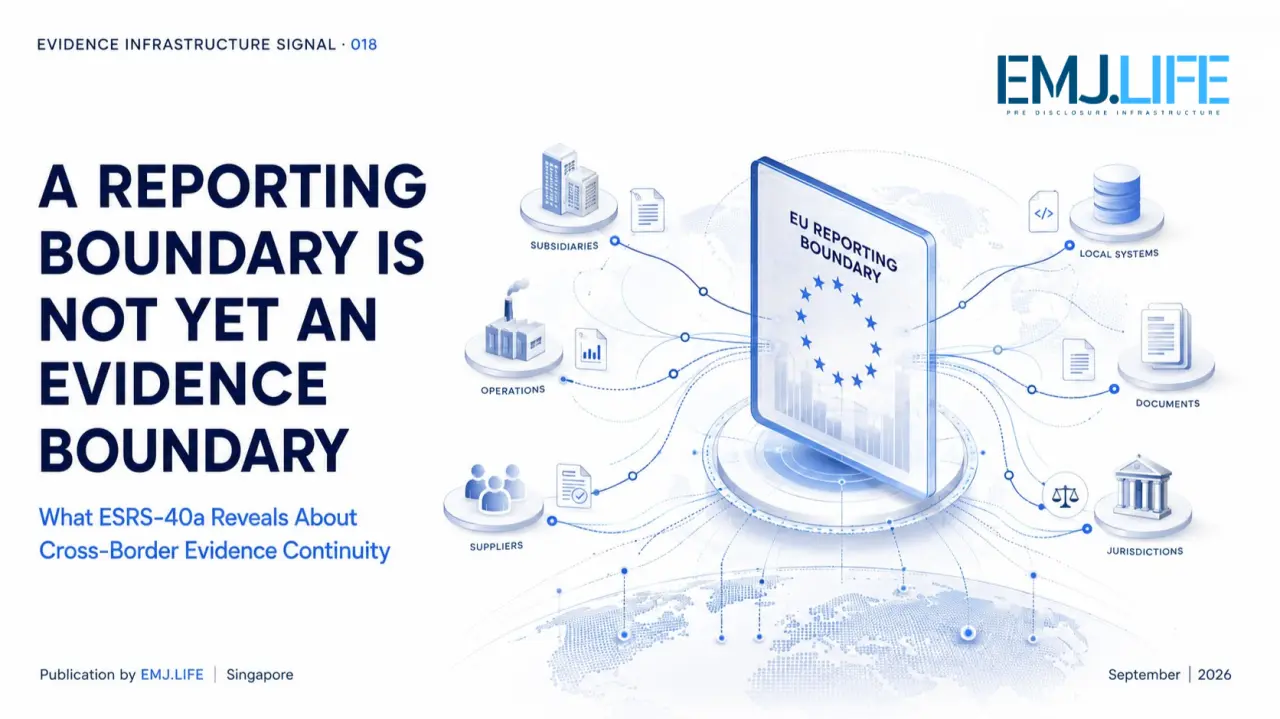
What ESRS-40a Reveals About Cross-Border Evidence Continuity
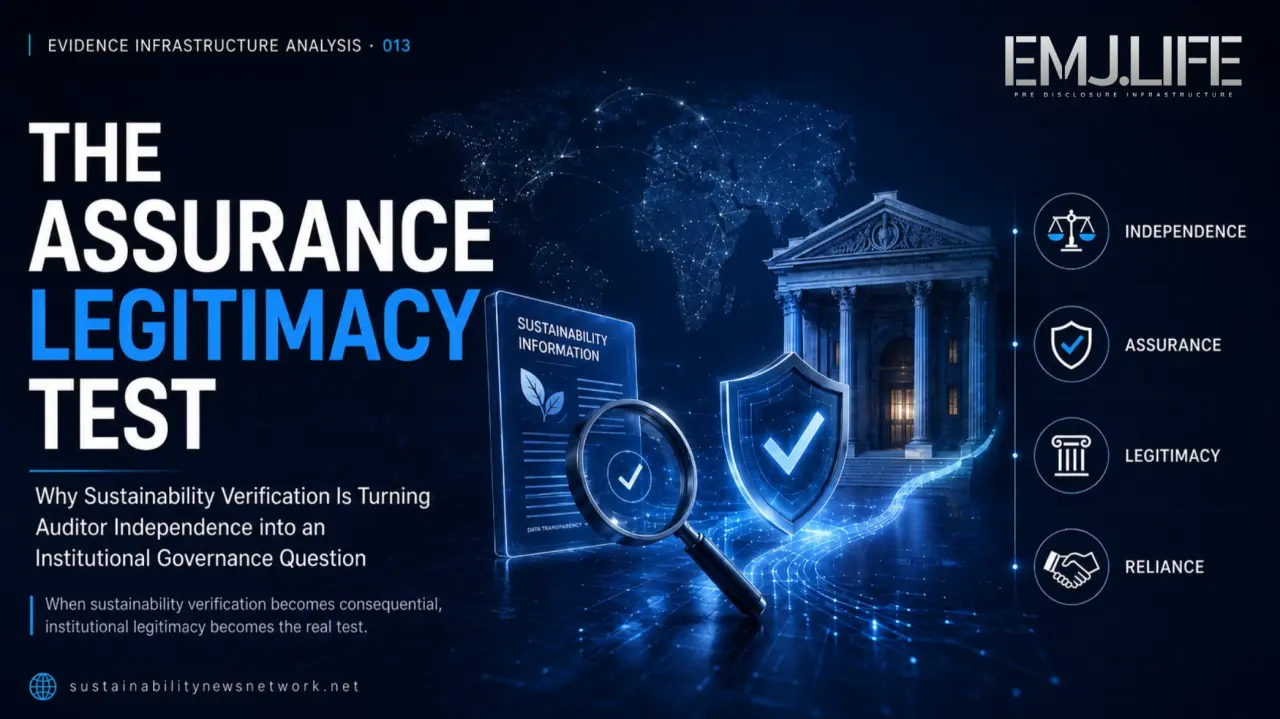
Why Sustainability Verification Is Turning Auditor Independence into an Institutional Governance Question
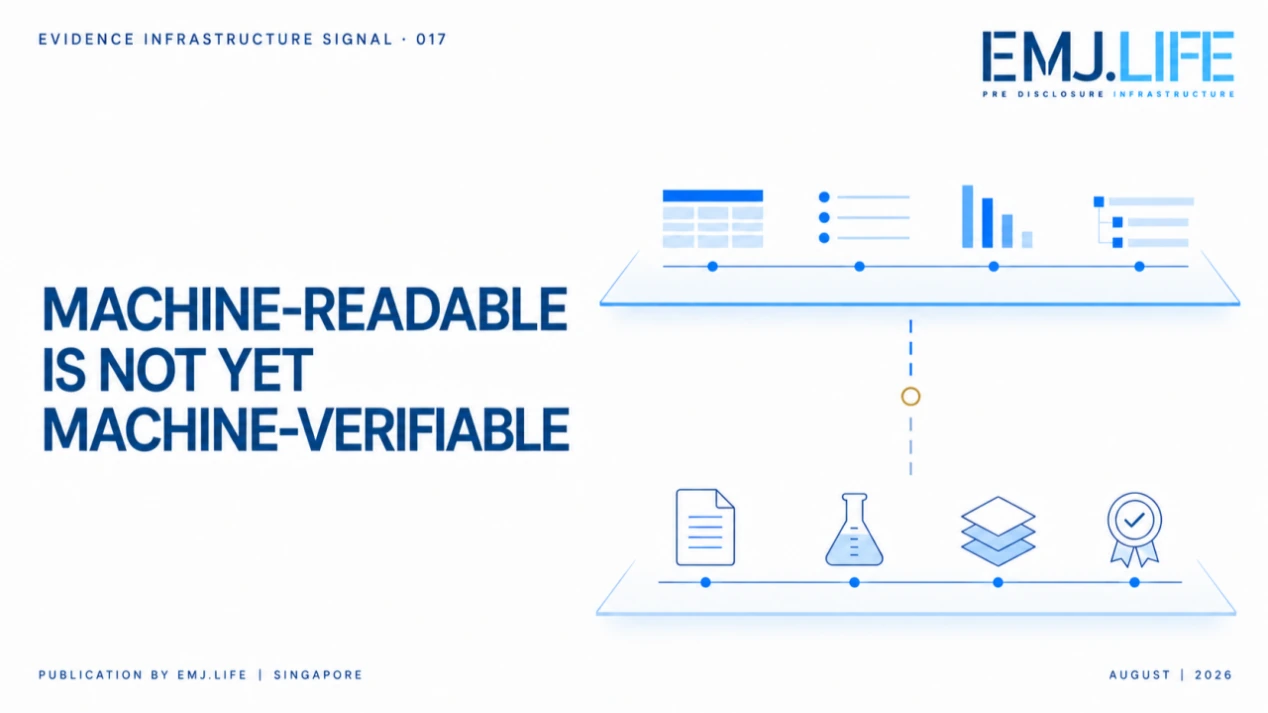
Why the IASB and ISSB Taxonomy Consultations Point to a Pre-Disclosure Evidence Gap
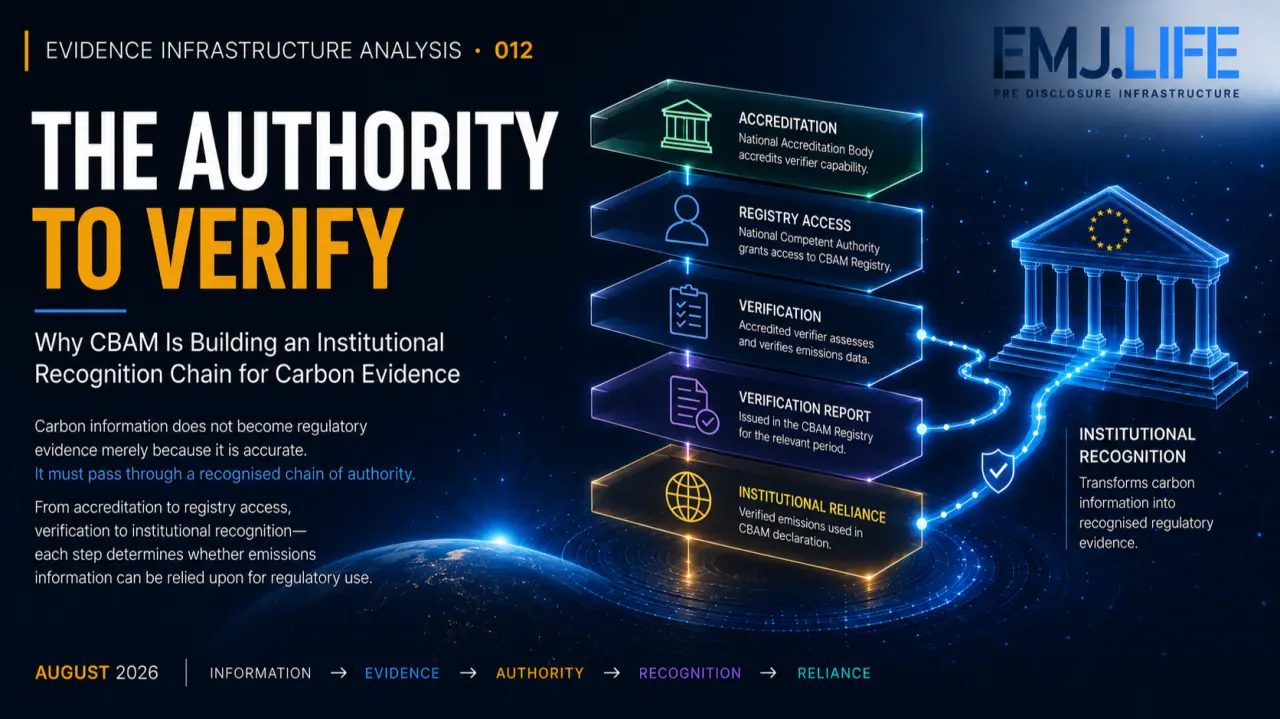
Why CBAM Is Building an Institutional Recognition Chain for Carbon Evidence
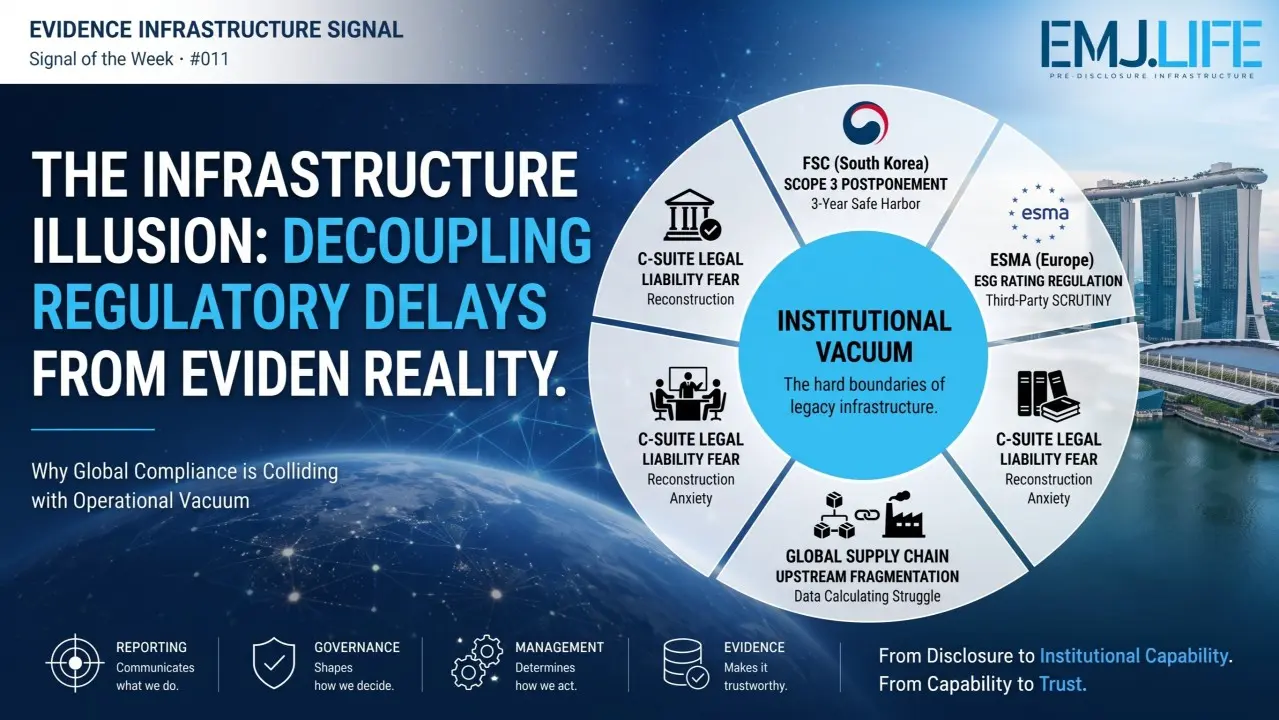
Decoupling Regulatory Delays from Evidential Reality
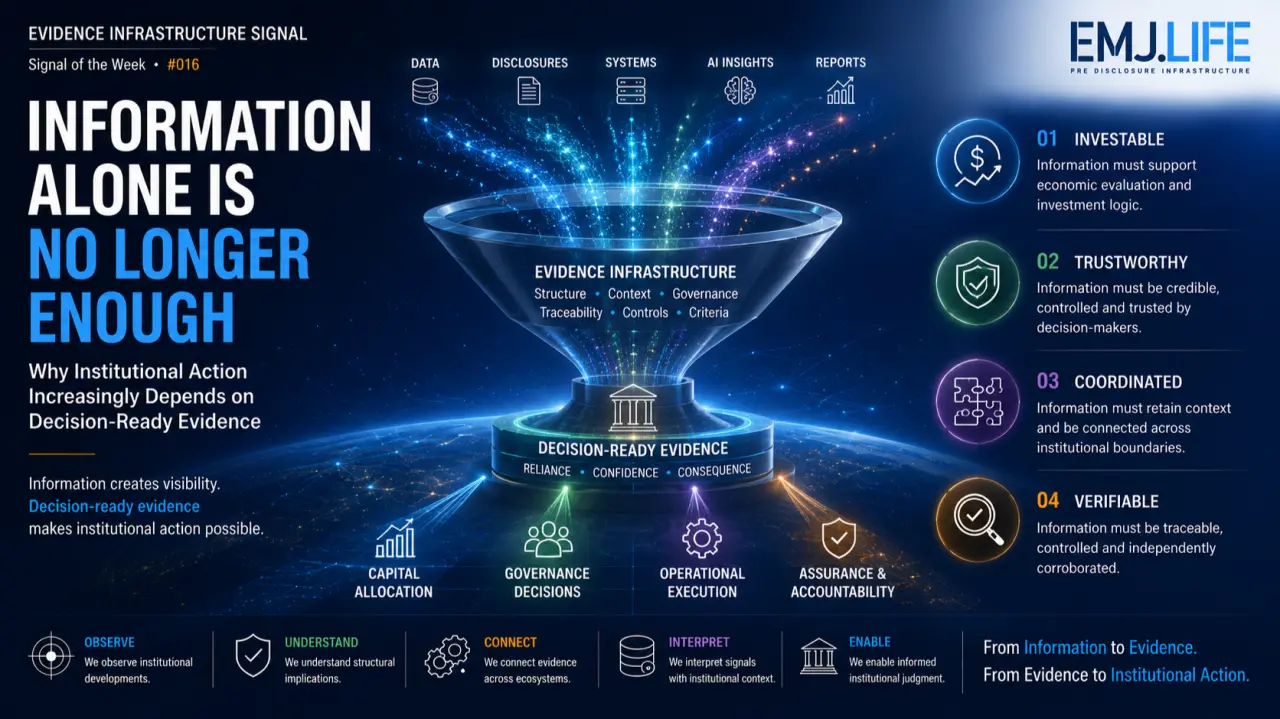
Why Institutional Action Increasingly Depends on Decision-Ready Evidence
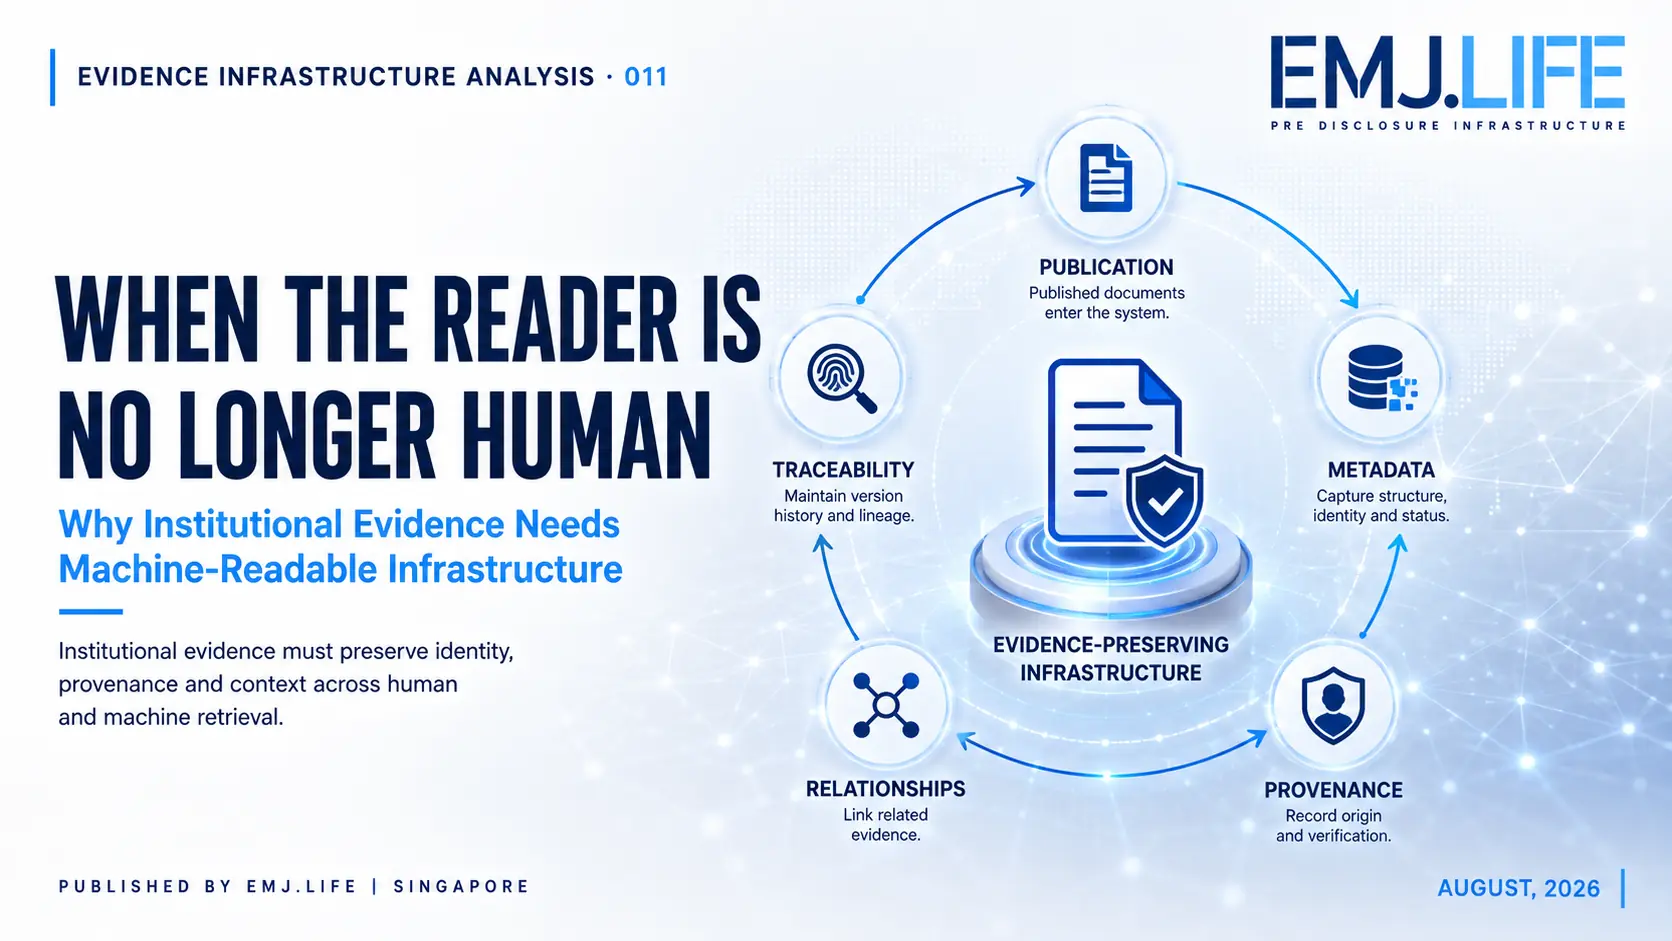
Why Institutional Evidence Needs Machine-Readable Infrastructure
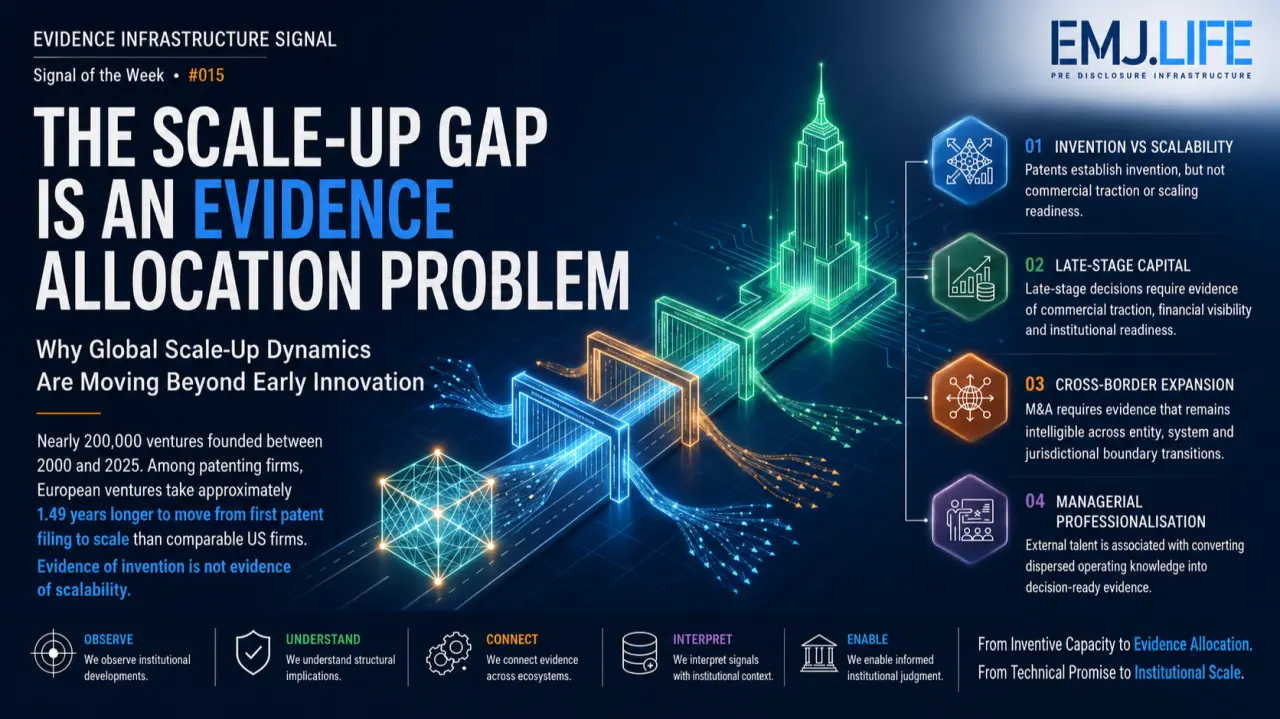
Why Global Scale-Up Dynamics Are Moving Beyond Early Innovation
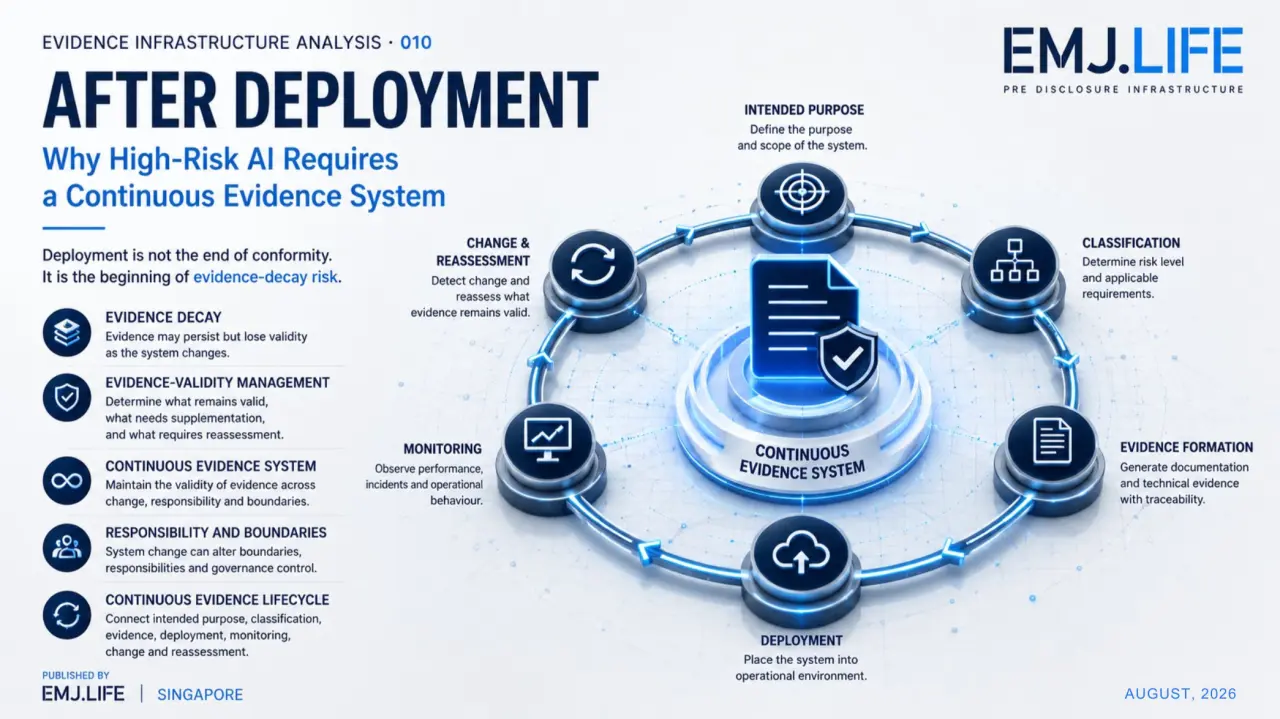
Why High-Risk AI Requires a Continuous Evidence System
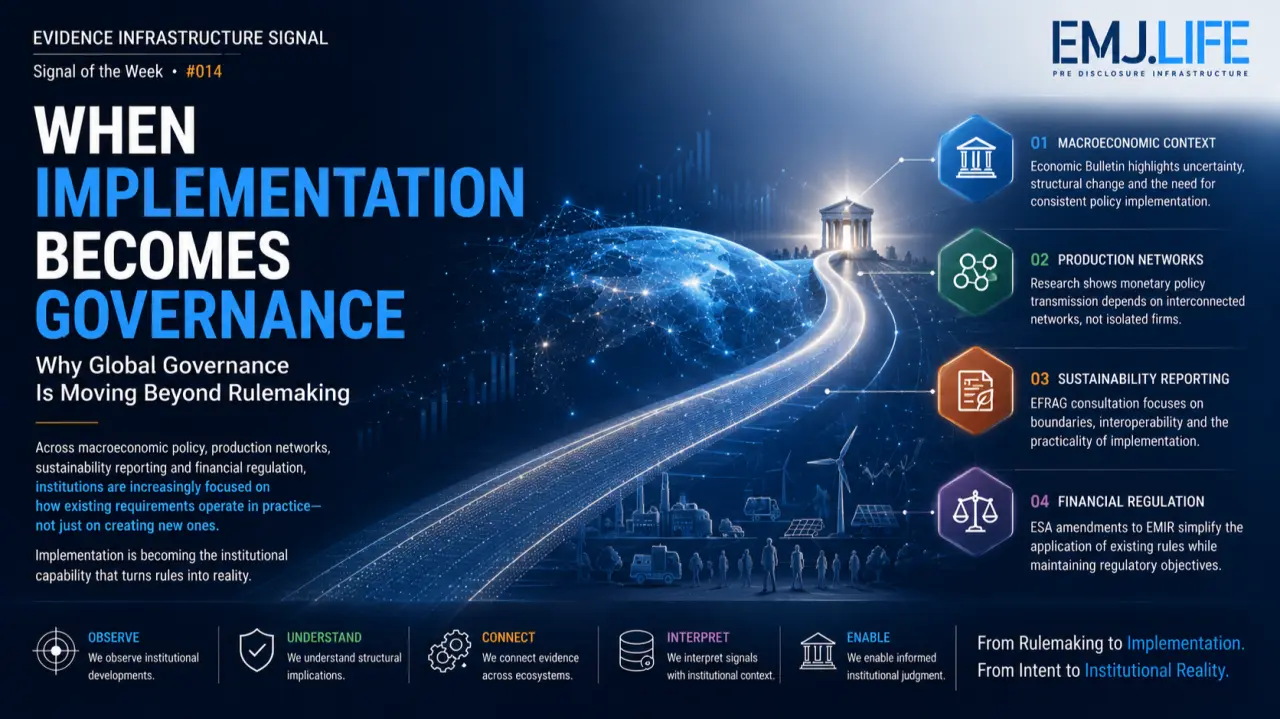
Why Global Governance Is Moving Beyond Rulemaking
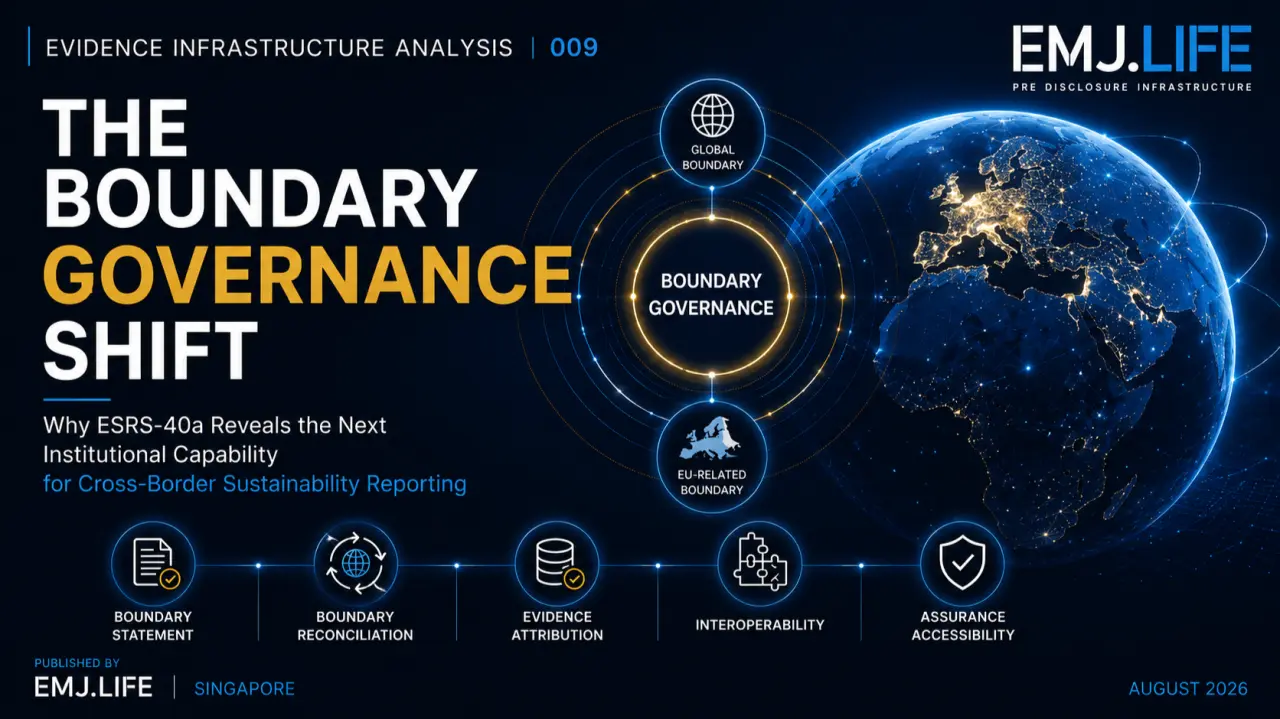
Why ESRS-40a Reveals the Next Institutional Capability for Cross-Border Sustainability Reporting
Why Sustainability Regulation Is Becoming Operational Infrastructure
Independent controlled external methodological supplement retained as a controlled draft record.
Published by EMJ.LIFE as an independent controlled external supplement referencing California Climate Accountability Laws.
Published by EMJ.LIFE as an independent controlled external supplement referencing European Union Carbon Border Adjustment Mechanism.
Published by EMJ.LIFE as an independent controlled external supplement referencing UNEP Finance Initiative.